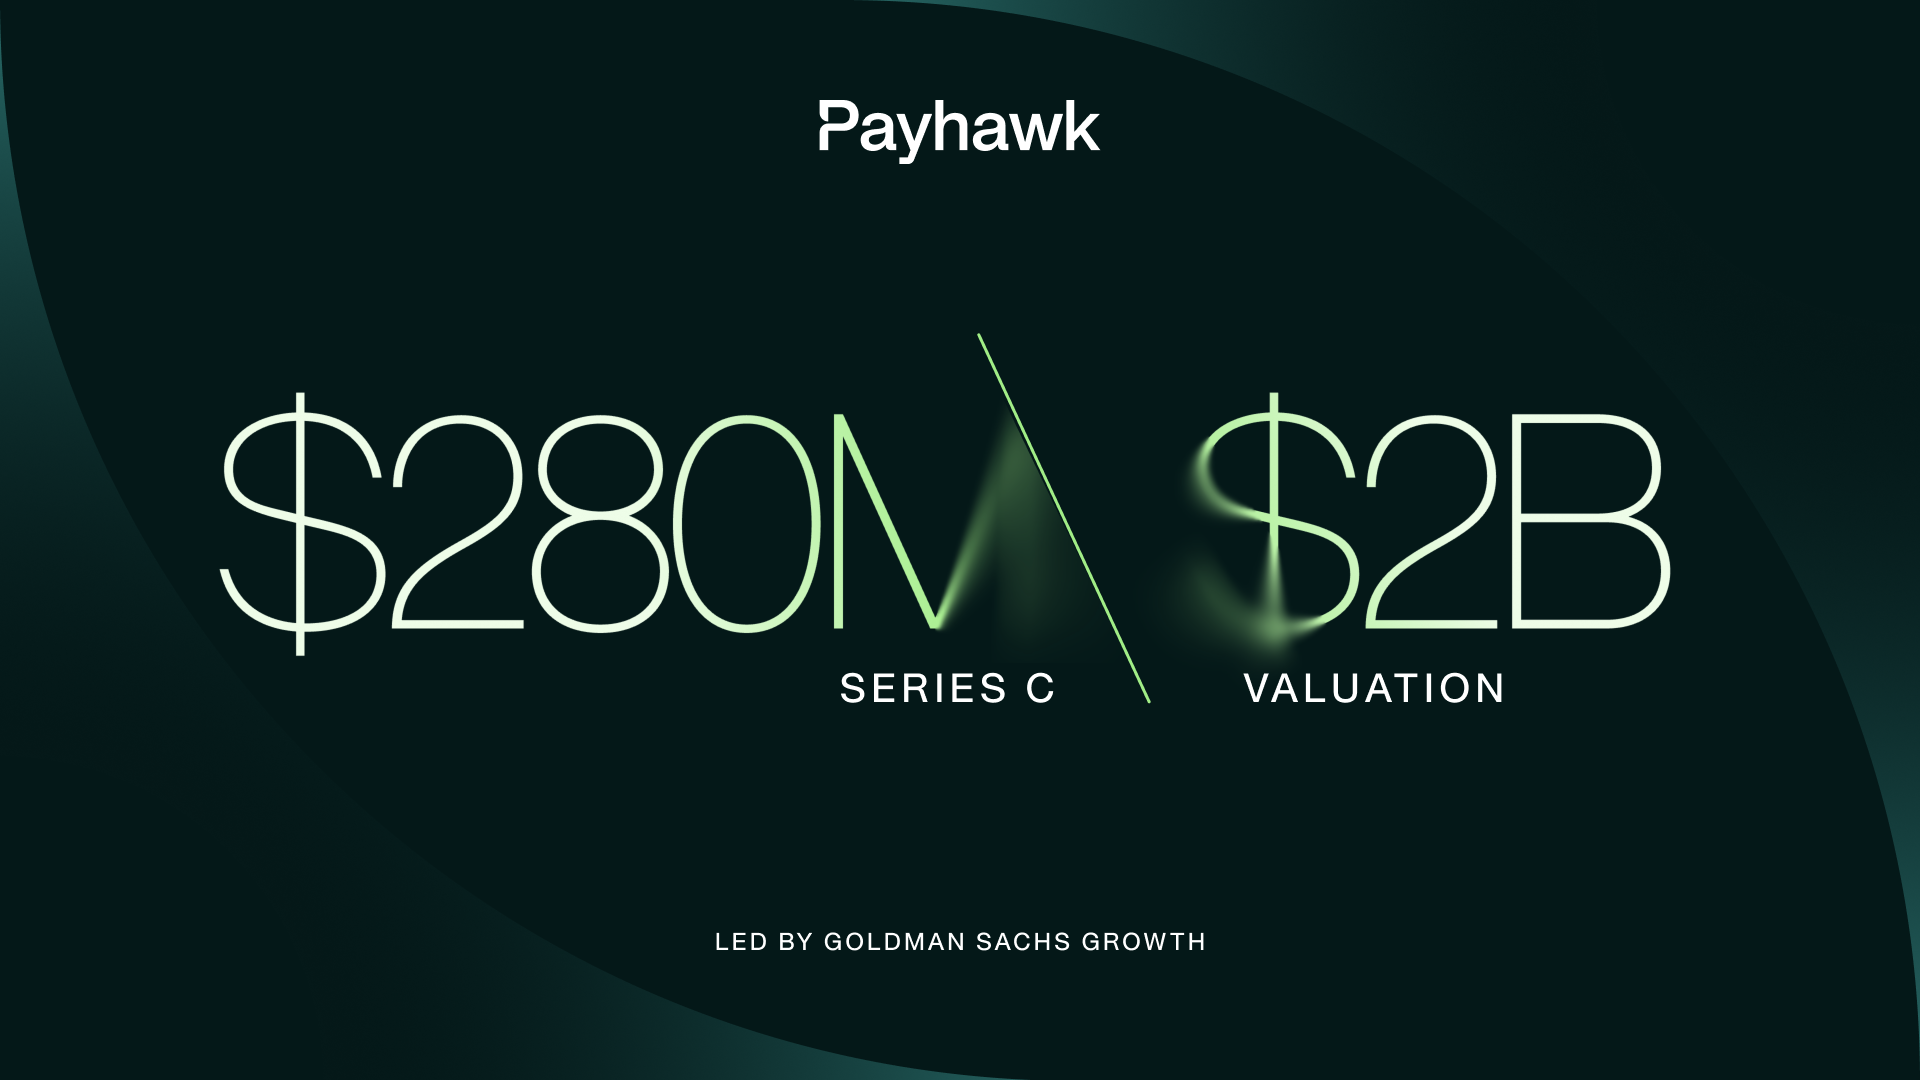
Payhawk has announced a $280 million all-equity Series C led by Growth Equity at Goldman Sachs Alternatives, valuing the company at $2 billion and bringing its total funding to more than $515 million. The deal remains subject to standard regulatory approvals. James Hayward, a managing director in Growth Equity at Goldman Sachs Alternatives, will join the board.
The eye-catching part of the announcement is not only the size of the round. Payhawk says it reached positive cash flow in the third quarter of this year and still holds 70 percent of the capital it raised in its 2022 round. That makes this a useful moment for founders to consider what a fundraise can signal when it isn’t framed as an urgent answer to a cash shortage.

A fundraise can be about speed, not survival
A company raising money while cash-flow positive and holding most of its previous round is in a different position from one raising because it needs cash to keep operating. Payhawk’s announcement points to a raise made from a place of financial breathing room, with the company pursuing a larger ambition: building what it calls a Finance Operating System for the AI era.
For founders, that distinction is worth studying. Capital is a tool, not a scorecard. A large round can be useful when it helps a business move faster toward a market opportunity, develop a product, or strengthen its position in a category. But raising money simply because it is available can also mean accepting expectations and obligations that don’t match the business’s needs.
The practical question is not “How much can we raise?” It’s “What specific progress could this capital help us achieve, and is funding the right way to achieve it?” That answer should be grounded in the company’s stage, economics, and goals, not the excitement of a headline.
Payhawk was founded in Sofia, Bulgaria, and now operates across 33 countries with 12 offices. Co-founder and CEO Hristo Borisov is positioning the business around a broad idea: not just improving separate finance tools, but changing how the finance function works as a whole.
The pricing lesson: what does your revenue reward?
One of the more transferable details in Payhawk’s story is its pricing model. The company says its business is built on subscription pricing rather than card interchange fees. Its argument is that this aligns the company’s growth with helping customers spend less, rather than earning more when customers spend more.
That is a useful prompt for any small business owner: What does your pricing reward?
A pricing model can shape a company’s incentives even when no one talks about those incentives directly. If your revenue rises when a customer buys more than they need, there may be tension between your growth and their best outcome. If you charge for ongoing value, saved time, or access to a service, the relationship may be easier to align, but the right answer depends on the business and what it delivers.
This isn’t a claim that one pricing model works for every company. It’s a reminder to look at the behavior your model encourages. Does your revenue grow when customers get more value? Are customers paying for outcomes they care about? Or are you benefiting when they spend more, even if that doesn’t make them better off?
For an independent founder, that question can reveal opportunities to build trust as well as revenue. It can also help explain your business more clearly: what customers pay for, why the price is fair, and how their success connects to yours.
Three layers for finance automation
Payhawk says it is building its Finance Operating System in three layers: AI agents that do financial work; payments infrastructure that lets those agents interact with money; and enterprise controls that define what an agent may do and when a human needs to make the call.

Borisov’s argument is that integrations connect systems and open protocols make information easier to access, but an operating system changes how the whole finance function works. That distinction matters more as software moves from suggesting actions to taking them.
For a small team, the key question is not simply whether automation can perform a task. It is whether you have decided what it is allowed to do, how you will review its work, and when a person must step in. A tool that recommends an action and a tool that makes a payment are not the same kind of responsibility.
Payhawk says 77 percent of its customers use its AI agents daily across financial control, procurement, travel, and reporting. That is the company’s own figure, and it reflects the adoption it reports across those areas. But for operators considering automation, daily use is only one part of the picture. Clear boundaries and reliable records matter too.
In the US, Payhawk says its Financial Controller Agent works with customers’ existing business cards, so customers do not have to switch card providers. That detail connects to another consideration for small businesses: keeping a paid alternative to your biggest single cost can help avoid dependence on one provider. A backup may cost something, but so can having no practical option if your main provider changes terms, becomes unavailable, or no longer fits your needs.
A one-month test before handing over more
You don’t need a major system overhaul to examine your approval rules. Try this small exercise before giving automation any more authority over finance:
- List routine money decisions. Write down recurring tasks such as categorizing expenses, checking receipts, or preparing payments.
- Sort them by risk. Mark which actions are low-value and easy to reverse, and which could create a meaningful financial or compliance problem if they go wrong.
- Set a clear boundary. Choose one low-risk task an automation tool may handle independently, and identify the amount, type, or condition that requires human approval.
- Keep a record. Note what the software did, what information it used, whether someone checked the result, and how any exception was resolved.
- Review after a month. Look for errors, unnecessary approvals, missing records, or decisions that should have been escalated.

The point is not to automate as much as possible. It is to learn where automation is dependable, where a person should stay involved, and whether the process leaves a trail that someone else can understand later. Start with a narrow task, define the rules before switching it on, and adjust based on what the month reveals.
Payhawk’s announcement puts several big ideas into one moment: raising from a position of financial strength, building around a clear category ambition, and thinking carefully about how incentives and controls shape a finance product. For small businesses, the takeaway is practical. Know what your next funding round is meant to buy, check what your pricing encourages, and decide what your tools can do before they act on your behalf.
Read the full story at digitalbuzznow.com.